
About us · Our founder
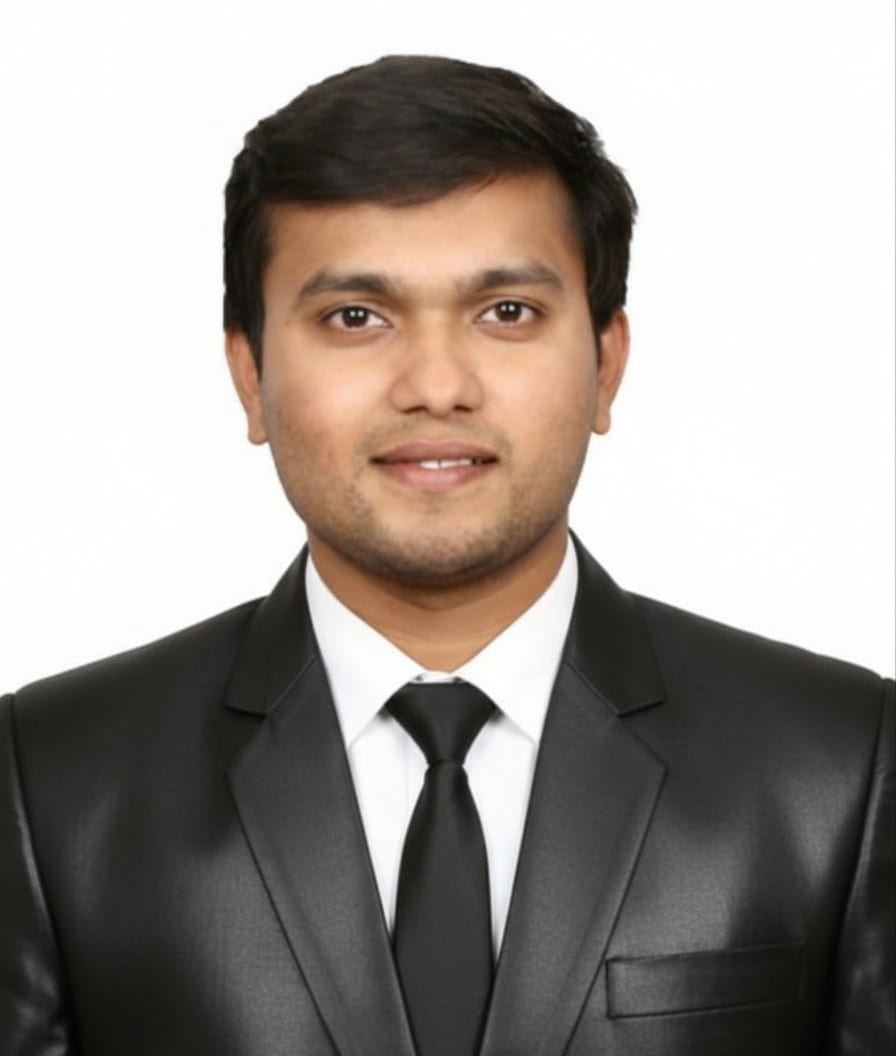
CA Devansh Shah
IBBI Registered Valuer, Securities or Financial Assets.
Chartered Accountant and founder of Fintellectual Valuation, Ahmedabad. Every Fintellectual report is scoped, led and signed by him, so clients always know who is responsible for the opinion.
 CA Devansh ShahFounder
- Registration
- IBBI Registered Valuer, Securities or Financial Assets
- Qualification
- Fellow Chartered Accountant (ICAI)
- Based in
- Ahmedabad, Gujarat
Profile
The valuer behind the firm.
CA Devansh Shah founded Fintellectual Valuation as a specialist practice doing valuation and related advisory only, with no audit or competing service lines. He is a Fellow Chartered Accountant and is registered with the Insolvency and Bankruptcy Board of India as a Registered Valuer for Securities or Financial Assets.
His work spans business and equity valuation, regulatory valuations under the Companies Act, FEMA, the Income-tax Act and SEBI regulations, Ind AS financial reporting valuations, startup and ESOP valuations, and intellectual property. Because Fintellectual is a single-professional practice, the person who scopes a mandate is the person who signs it.
Credentials & compliance
Registrations can be verified on the IBBI public register of valuers and with ICAI.
- Chartered Accountant
- Fellow member, Institute of Chartered Accountants of India · Membership no. 194193
- IBBI Registered Valuer
- Securities or Financial Assets, under Section 247 of the Companies Act, 2013 · Registration no. IBBI/RV/16/2024/15567
- Registered Valuers Organisation
- Member, Assessors and Registered Valuers Foundation (AaRVF)
- Standards
- ICAI Valuation Standards and International Valuation Standards
Compliance · Standards
Standards we report to.
ICAI
ICAI Valuation Standards
Indian standards for engagement conduct, documentation and reporting.
IVSC
International Valuation Standards
The global framework for bases of value, approaches and reporting.
RVO
Registered valuer norms
Conduct, competence and continuing education.
Compliance · Frameworks
Regulatory frameworks we report under.
| Framework | What we provide |
|---|---|
| Companies Act, 2013 | Registered valuer reports under Section 247, including Sections 62 and 230–232. |
| Income-tax Act, 2025 | Fair market value under Rule 57 of the Income-tax Rules, 2026 (formerly Rule 11UA), for Sections 79 and 92(2)(m), and documentation for Section 102 (formerly section 68). |
| FEMA | Pricing for cross-border issue and transfer of shares under the NDI Rules, 2019. |
| SEBI | Valuations required under SEBI regulations, including the AIF Regulations. |
| IBC, 2016 | Fair value and liquidation value. |
| Ind AS | Ind AS 113, 103, 36 and 102. |
Transactions and returns for FY 2025-26 and earlier remain governed by the Income-tax Act, 1961 and the Income-tax Rules, 1962. Provisions are confirmed against the notified text at scoping.
Areas of expertise
Where the work concentrates.
Business & equity
Business valuation
For transactions, restructuring, shareholder matters and disputes.
Regulatory
FEMA, Income-tax, Companies Act, SEBI
Valuations prepared for the AD bank, the tax officer, the NCLT or the regulator.
Transactions
M&A valuation
Deal pricing, share exchange ratios and fairness support.
Financial reporting
Ind AS valuation
Fair value measurement, purchase price allocation and impairment testing.
Startups & ESOPs
Early-stage equity
Rounds, convertibles, CCPS, option pricing and 409A for US-parent startups.
Intangibles
IP valuation
Patents, trademarks and brands, software and technology know-how.
Published articles
Articles and technical contributions.
Tax · Regulation
After angel tax: how share premium is examined under the Income-tax Act, 2025
Section 102, Section 92(2)(m), Rule 57 and the FEMA floor.
Tax · Regulation
Rule 11UA is now Rule 57
What moved in the Income-tax Rules, 2026, and what stayed.
Methodology
DCF or comparable companies: which does your valuation need?
When each method should carry the conclusion.
ESOP · Compliance
Three mistakes that get ESOP valuations rejected by auditors
Stale dates, mixed purposes and unsupported inputs.
Reference
Valuation glossary
Terms used in reports, term sheets and tax notices.
Professional memberships
Memberships and profiles.
Institute of Chartered Accountants of India
Fellow member
Insolvency and Bankruptcy Board of India
Registered Valuer, Securities or Financial Assets
Assessors and Registered Valuers Foundation (AaRVF)
Member
Selected case studies
Anonymised engagements, and the review each faced.
Investor diligence
SaaS fundraising
A Series A valuation through three rounds of investor diligence without a methodology objection.
AD bank · Auditor
Manufacturing, cross-border transfer
A FEMA valuation accepted by the AD bank and auditor on first submission.
Fund auditor · LPs
Fund fair value
A venture fund’s move to independent quarterly marks.
Contact
Speak directly to the valuer who will sign your report.
Share the purpose, the parties and the date that matters. You will hear back from CA Devansh Shah within one business day.